The is one of the most recognizable premium travel rewards cards on the market, offering everything from airport lounge access and hotel elite status to a long list of travel and lifestyle statement credits.
But with an $895 annual fee (see rates and fees), it’s also a significant investment.
The Amex Platinum offers plenty of opportunities to offset that cost, especially if you travel frequently and can take advantage of its statement credits. However, many of its benefits come with restrictions, and getting the full value requires some effort.
So, who can actually get enough value from the Amex Platinum to justify its annual fee? Let’s take a closer look at who should — and shouldn’t — consider adding this card to their wallet.
Who should get the Amex Platinum?
People who will use the lounge access
For frequent travelers, airport lounge access is one of the biggest reasons to consider the .
The card offers access to one of the most extensive airport lounge networks available through a credit card, making it especially valuable if you spend a lot of time in airports.
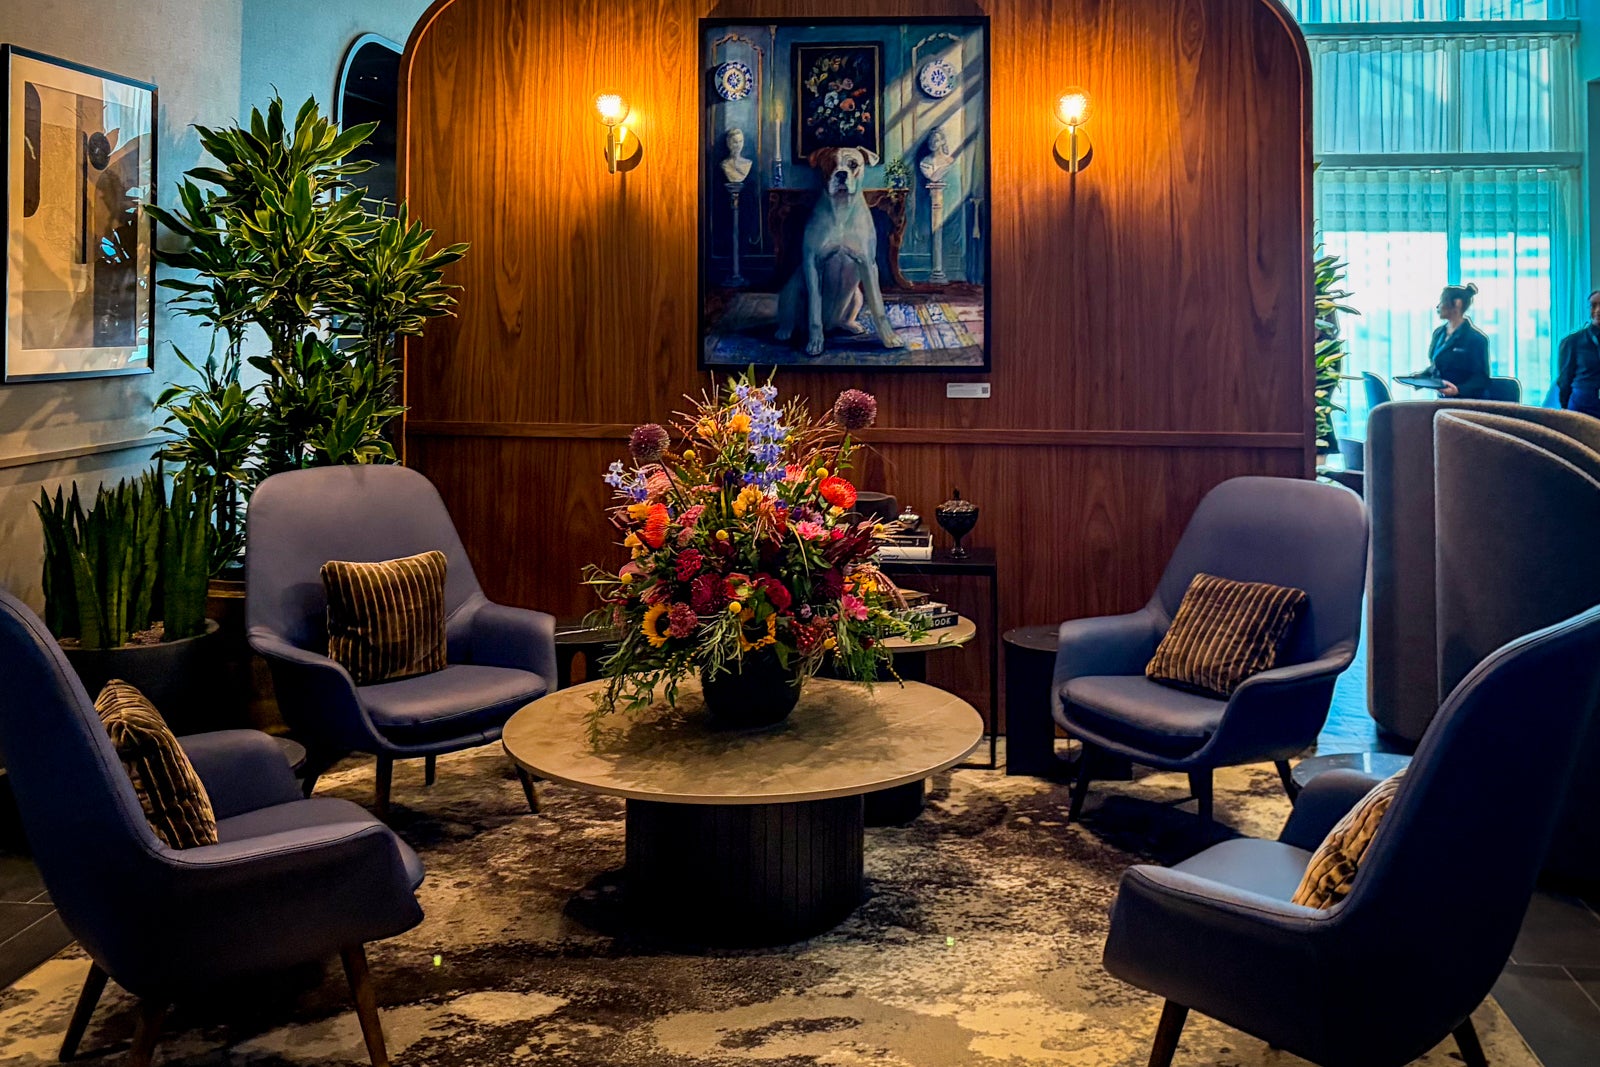
Cardmembers can access American Express Centurion Lounges, receive a Priority Pass Select membership (enrollment required) and visit Delta Sky Clubs when flying on eligible same-day Delta flights. Delta Sky Club access is limited to 10 visits per year unless you spend $75,000 on eligible purchases in a calendar year to unlock unlimited visits. Access is subject to eligibility requirements.
Amex also operates Centurion Lounges at more than 20 airports, so the benefit can be particularly valuable if you live near or frequently connect through an airport with one.
If you travel frequently and would otherwise pay for lounge access, the Platinum could help you save money while making your time at the airport more comfortable. And when combined with the card’s other travel benefits and statement credits, lounge access can help make the $895 annual fee easier to justify.
People who can maximize the lifestyle credits
While the is best known for its premium travel benefits, it also offers a growing list of lifestyle statement credits that can help offset its $895 annual fee.
For example, cardmembers can receive up to $400 in Resy statement credits each calendar year (distributed as up to $100 per quarter) at eligible U.S. Resy restaurants* and up to $300 in Lululemon statement credits* (up to $75 quarterly) at U.S. stores (excluding outlets) and online.
The card also offers up to $300 annually in digital entertainment statement credits* (up to $25 monthly) for eligible subscriptions, along with up to $120 annually toward an Uber One membership to fully cover an auto-renewing $96 annual or $9.99 monthly membership*.
*Enrollment is required

If you’re already spending money on dining, shopping and entertainment in these categories, the credits can provide meaningful value without requiring you to change your spending habits.
However, many of these benefits are divided into monthly or quarterly credits, so you’ll need to keep track of when to use them. The Platinum is a particularly good fit for someone who doesn’t mind managing these benefits and can consistently take advantage of them year-round.
Related: How to maximize benefits with the American Express Platinum
People who stay at Hilton, Marriott or select luxury hotels
The Amex Platinum can also be a valuable addition to your wallet if you regularly stay at Hilton, Marriott or luxury hotels.
Cardmembers receive complimentary Hilton Honors Gold and Marriott Bonvoy Gold Elite status, which can provide benefits such as bonus points on stays and potential room upgrades. You’ll also receive Leaders Club Sterling status with The Leading Hotels of the World, a collection of independent luxury hotels. Enrollment is required for select benefits.
Beyond elite status, one of the Platinum’s most valuable hotel-related perks is its up to $600 annual lodging statement credit (up to $300 semiannually).
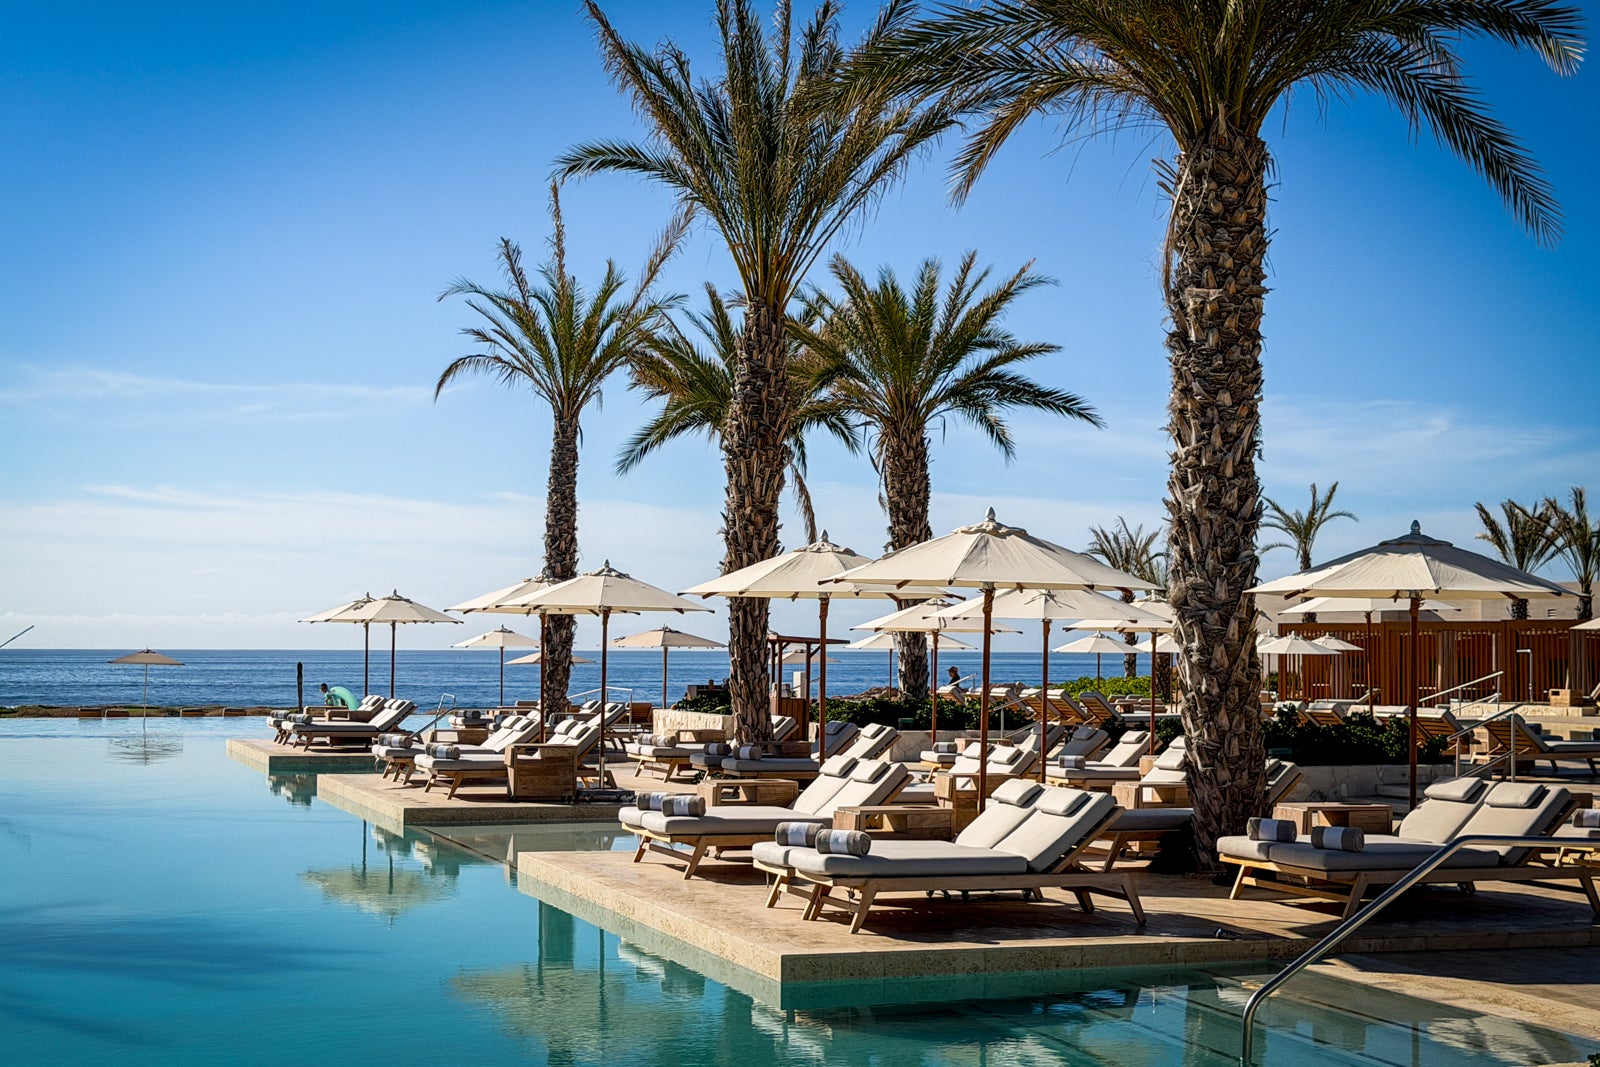
Cardmembers can receive up to $300 in statement credits every six months on eligible prepaid bookings through American Express Travel®, including stays at Fine Hotels + Resorts and The Hotel Collection properties, as well as select Airbnb Luxe stays.
The Hotel Collection and Airbnb Luxe require a minimum two-night stay, and beginning Jan. 1, 2027, Fine Hotels + Resorts bookings will also require at least two nights to qualify for the lodging credit.
Fine Hotels + Resorts bookings also come with valuable benefits, including daily breakfast for two, guaranteed 4 p.m. late checkout, room upgrades when available and a property credit valued at $100.
If you regularly book these types of stays, the lodging credit and additional perks can go a long way toward offsetting the card’s annual fee. Just be sure to compare prices with booking directly, since rates through Amex Travel aren’t always the lowest.
Related: How to maximize the Amex Platinum hotel statement credit
People who are over Chase’s 5/24 rule
Chase’s unofficial 5/24 rule generally makes applicants ineligible for many Chase cards if they’ve opened five or more personal credit cards across issuers within the past 24 months.
Travelers who are still eligible for Chase cards may want to prioritize products such as the (see rates and fees) or (see rates and fees) before exceeding that threshold.

If you’ve already built a collection of Chase rewards cards, the Amex Platinum could be worth considering as your next premium travel card.
The card also earns Membership Rewards points, giving you access to a separate collection of airline and hotel transfer partners that can complement an existing Chase Ultimate Rewards strategy.
Who shouldn’t get the Amex Platinum?
People under 5/24
Many people just starting in the points world underestimate the stringency of Chase’s 5/24 rule. If you’re just getting started with travel rewards and remain under Chase’s 5/24 threshold, you may want to think carefully before applying for the Amex Platinum.
Opening the card could count toward your 5/24 total and potentially limit your eligibility for Chase cards in the future. That could mean missing out on valuable welcome offers or benefits from cards you planned to open later.
However, once you get over 5/24, it may be hard to get back under, and there’s a massive opportunity cost in doing so. Having a plan and sticking to it will serve you well in the long term.
Of course, that doesn’t mean everyone under 5/24 should avoid the Platinum. If its benefits are a particularly good fit for your travel habits, it may still make sense.
People who book airfare through online travel agencies
The provides 5 Membership Rewards points per dollar spent on flights booked directly with airlines or with American Express Travel (on up to $500,000 of spending each calendar year, then 1 point per dollar spent).
A card like the or (see rates and fees) may be a better fit because their broader travel earning categories can include eligible third-party airfare bookings.
People who can’t maximize the Platinum’s statement credits
The offers a long list of statement credits, but that doesn’t necessarily mean every cardholder will get enough value from them to justify the $895 annual fee.
Following the card’s 2025 refresh, several of its benefits are geared toward specific lifestyle purchases, including dining at Resy restaurants, shopping at Lululemon and purchasing an Oura Ring. (Cardmembers receive up to a $200 Oura Ring statement credit each calendar year. This statement credit applies to ring purchases only and doesn’t cover subscriptions. Enrollment is required.)
Many of these credits also come with restrictions. For example, the Resy and Lululemon credits are distributed quarterly, meaning you’ll need to use them throughout the year rather than all at once.
If you don’t already spend money with these merchants, or you don’t want to keep track of multiple credits and enrollment requirements, the Platinum may not be the best fit.
Before applying, carefully consider just how much these credits are worth to you; if they provide little to no value, another Amex card might be a better fit.
Related: 4 different flavors of Amex Platinum — which one is right for you?
People who’d be better off with the Amex Business Platinum Card
Business owners with substantial expenses may find that is a better fit than the personal Platinum.
Although both cards carry an $895 annual fee (see rates and fees), their earning rates and statement credits differ in ways that could make one more valuable than the other.
For example, the Business Platinum earns 2 points per dollar spent on eligible purchases in select business categories and on purchases of $5,000 or more, on up to $2 million in combined eligible purchases per calendar year, then 1 point per dollar.
The Business Platinum also provides up to $1,150 in statement credits per calendar year for U.S. Dell purchases: up to $150 each calendar year and an additional $1,000 statement credit after spending $5,000 on Dell purchases with the same card each calendar year (enrollment required).
You can also access the Pay with Points redemption option on the Business Platinum card, which gets you a 35% bonus for eligible flights with your selected airline using your Amex points (up to 1 million points back per calendar year). This is notably not available on the personal Amex Platinum.
These business-focused benefits may be more useful for someone with significant company expenses, while the personal Platinum may be a better fit for travelers who can maximize its lifestyle credits.
When to apply for the Amex Platinum
New cardmembers can find out their offer and may be eligible for as high as 175,000 bonus points after spending $12,000 on purchases in the first six months of card membership. (Welcome offers vary, and you may not be eligible for an offer.)
Based on TPG’s November 2026 valuations, that bonus could be worth up to $3,500, which is nearly four times the card’s $895 annual fee.
While this is the card’s standard welcome offer, now could still be a good time to apply if you’re eligible for an offer you’re happy with and can comfortably meet the spending requirement without making unnecessary purchases.
Just make sure you’ll also get enough value from the card’s ongoing benefits to justify its annual fee beyond the first year.
Related: The best time to apply for Amex cards based on offer history
The offers an impressive lineup of premium travel benefits and statement credits, but its $895 annual fee means it won’t make sense for everyone.
For frequent travelers who value airport lounge access and luxury hotel perks, and can consistently use the card’s lifestyle credits, there’s plenty of potential to get more value than the annual fee.
On the other hand, travelers who prefer straightforward rewards or don’t regularly use the card’s benefits may find better value with a lower-annual-fee option.
Ultimately, the Platinum is worth considering if its benefits fit your existing spending and travel habits — not because of the total advertised value of its credits.
To learn more, check out our full review of the Amex Platinum.
Apply here:
For rates and fees of the Amex Platinum Card, click here.
For rates and fees of the Amex Business Platinum Card, click here.